

Well, it happened … in August, I turned the BIG 4-0! Honestly, I’ve kind of felt like I was 40 for the last ten years, so it’s really not much different. One thing that this old man has noticed lately is “Help Wanted” signs posted just about everywhere. As the economy officially printed its second quarter GDP at 4.1% according to the Bureau of Labor Statistics, and the official unemployment rate is wavering between 3.8% and 4%, it seems like even local McDonald’s restaurants are looking to hire at above $11/hour. Bank tellers I’ve asked are starting at $12/hour and more seasoned vets are now making $15/hour. Employment demand is outpacing people looking for work and it is resulting in average wages starting to make notable increases. This is a good thing, being that it has felt like wages really haven’t moved in about a decade!
I’m not writing this article about how well the economy is doing; I want to focus on what folks should be doing with those newfound raises or newly-found employment income. The first thing I encourage budgeters to do is to build an emergency fund. I urge clients to aggressively save enough money in a bank account to get them through a “rough patch.” Once that is done, you can start socking away some money into an employer-sponsored retirement plan or individual retirement account (IRA). Lastly, I would encourage everyone to start a Rainy-Day Fund.
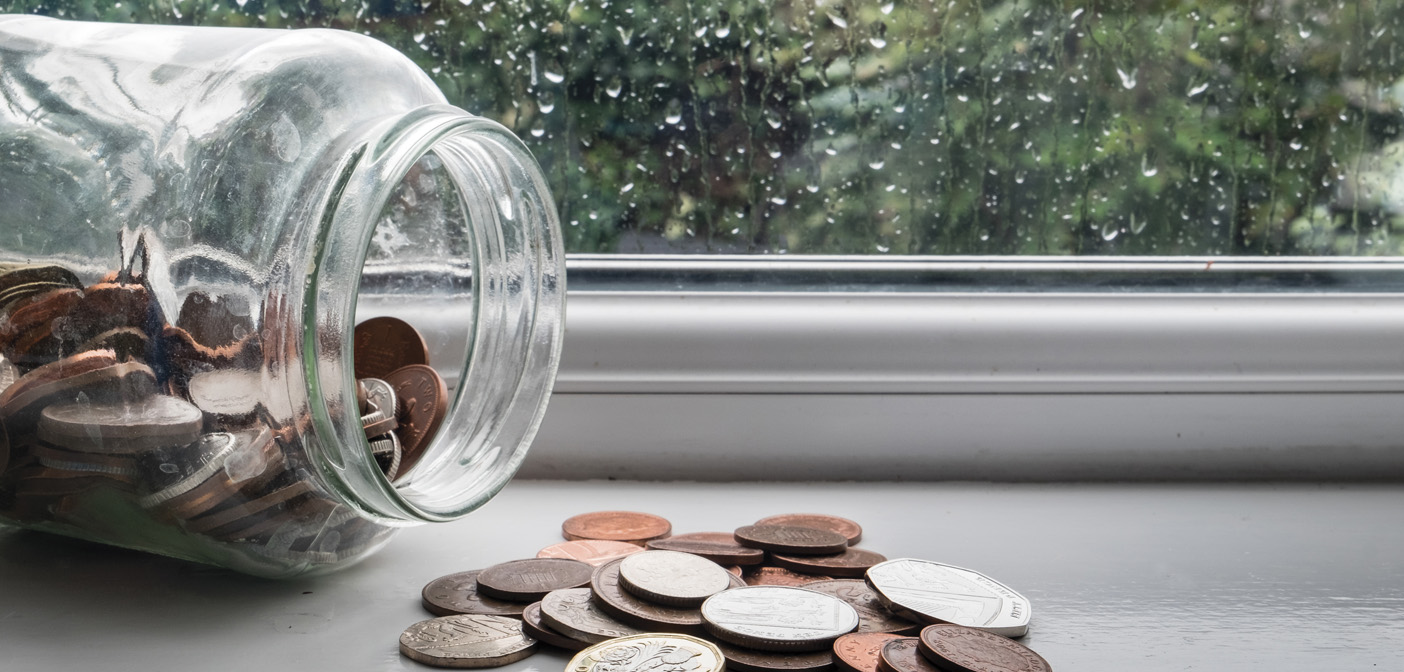
I view the Rainy-Day Fund as something slightly different than the emergency fund. Emergency funds are there to cover large, unexpected periods of time when, for some reason, your income stream has been altered or interrupted. This fund should be kept separate so that once saved, we never dip into it unless there is truly an emergency. I view a Rainy-Day Fund as money that can help with unexpected expenses, not unexpected periods without income. Unexpected expenses might be something like: your car’s transmission goes out, your taxes were prepared incorrectly and you owe the IRS, you get a speeding ticket, or perhaps your unattractive kid gets invited to prom and now you have to buy the fancy outfit. (Just kidding on the last part.) The Rainy-Day Fund is just a small stash of money that’s there for life’s everyday “oopsie.”
Now that the economy is doing better and you may have gotten a raise or a promotion, I would encourage you to start systematically saving a small amount to help pay for these annoyance expenditures. I’m not talking about anything crazy here, but possibly give up your daily mocha and start putting that money in an account for a rainy day. It can add up quickly! A $20 weekly savings adds up to $80 a month and then, a year later, you’re looking at $1,000 saved for that rainy-day expense. So, in short, don’t let this increasing wage environment go to waste. Start slowly putting money into your newly-established Rainy-Day Fund.